What is Cash Discount?
A Direct Incentive for Cash Transactions
Cash Discount is a pricing strategy where a merchant displays the regular price of an item inclusive of credit card processing fees. Customers who pay using cash receive a percentage discount off that displayed price, effectively eliminating processing costs for that sale.
Customer Experience
The register automatically applies the discount when cash is tendered. Receipt itemization clearly shows the applied dollar savings, making the reward for paying with cash transparent at the point of sale.
Compliance Safeguard
Card brands require clear signage at entrance points and the register detailing the cash incentive, along with automated receipt line items showing the applied reduction. We provide official point-of-sale notices, configure terminal receipt output, and oversee the entire implementation process to ensure complete network adherence.

The register applies the cash discount automatically at checkout, printing clear line-item reductions on consumer receipts without manual cashier intervention.

Signage and menu layouts disclose regular price points alongside discounted cash incentives, ensuring patrons understand total checkout costs before ordering.
What is Dual Pricing?
Clear Side-by-Side Pricing at Checkout
Dual Pricing is a strategy where a business displays two distinct prices for an item or service: a standard higher price for credit or debit card users, and a discounted lower price for customers paying with cash.
Customer Experience
Card and cash options are displayed simultaneously on shelf tags, menus, and customer-facing terminal screens, allowing patrons to choose their preferred method without surprises.
Compliance Safeguard
Regulatory rules mandate that card and cash values be visible simultaneously on shelf tags, service menus, and the customer-facing payment screen prior to payment. We supply compliant display templates, program terminal firmware for simultaneous rate calculations, and manage the complete rollout from start to finish.

The customer-facing payment terminal presents both card and cash totals simultaneously, leaving the final payment method entirely to patron preference.

Every tag and price sheet displays both payment values side-by-side, removing checkout surprises and reinforcing fair, upfront business practices.
What is Surcharging?
Passing Credit Processing Costs at the Register
Credit card surcharge is an extra fee that a merchant adds to a transaction when a customer pays with a credit card. This fee passes the cost of processing credit card interchange and network fees from the business to the consumer. Surcharges are typically limited to a maximum percentage and must be clearly disclosed before checkout.
Customer Experience
Debit card transactions remain completely exempt from additional fees. When an eligible credit card is processed, the compliant fee is calculated dynamically and shown prior to final approval.
Compliance Safeguard
Visa currently flags U.S. Visa surcharges above 3%, while Mastercard rules cap surcharges based on merchant cost and applicable maximums. Card-network and state regulations differ. We guide you through a current compliance review for your exact setup.

Our terminal software automatically identifies debit versus credit cards, applying surcharges solely to eligible credit transactions while remaining fully compliant with network caps.
How Do You Secure Lower Processing Rates?
Understanding Interchange & Wholesale Costs
Interchange rates are non-negotiable wholesale fees charged by card-issuing banks for processing electronic card transactions, set by major card brands like Visa, Mastercard, and American Express. While interchange itself cannot be changed, the total rate a business pays is absolutely adjustable, which is where transparent fee auditing creates direct savings.
Customer Experience
Zero checkout alterations at the counter or website cart: Customers pay their standard balance, while your business retains higher revenue through wholesale pass-through billing.
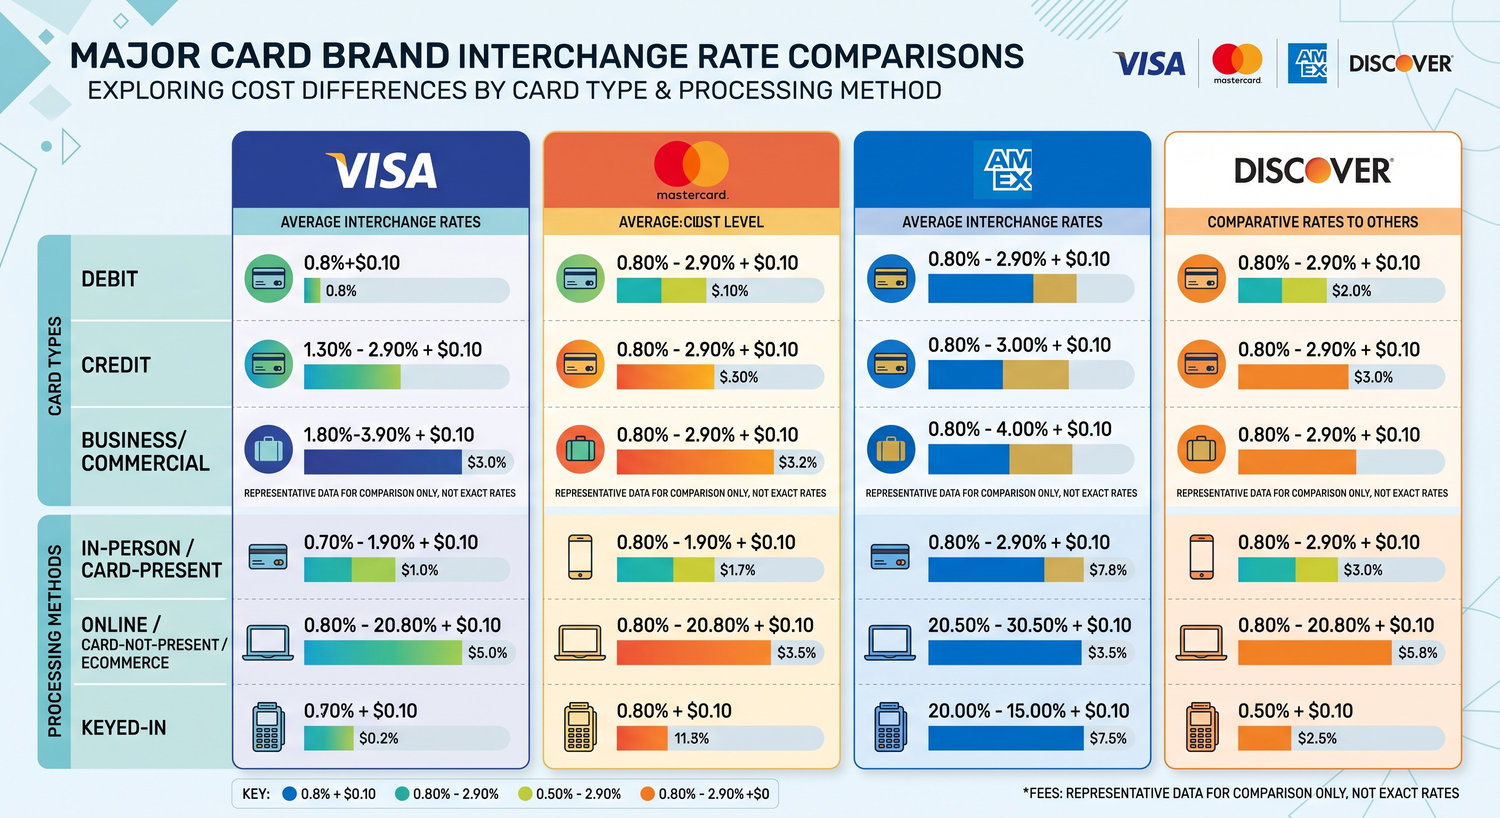
By eliminating unnecessary processor markups and routing transactions through clean interchange-plus billing, your business retains more revenue on every swipe without changing customer checkout behavior.
Unsure Which Setup Fits Best?
We are here to provide an honest review of your current setup, answer your questions without pressure, and guide you toward a path forward that makes sense for your business.